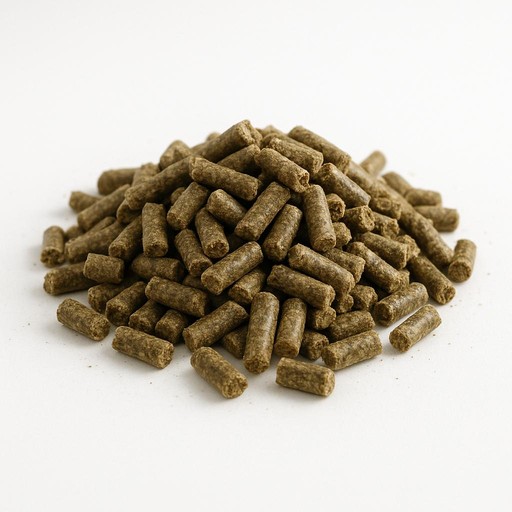
Beef Cow Feed 공급업체, 무역 및 가격 — 마켓 오버뷰 2026
상위 제품
Cattle Feed
최종 업데이트
2026-10-19
서치 및 소싱 팀을 위한 핵심 요약
- Beef Cow Feed 마켓 커버리지는 40개 국가에 걸쳐 있습니다.
- 이 제품에 대해 글로벌 공급망 인텔리전스 네트워크에 수출업체 331개와 수입업체 398개가 색인되어 있습니다.
- 625건의 공급업체 연계 거래가 상위 20개 국가에 걸쳐 요약되어 있습니다.
- 페이지 데이터 최종 업데이트일: 2026-10-19.
Beef Cow Feed에 대한 글로벌 공급업체 거래, 수출 활동 및 가격 벤치마크
상위 20개 국가에 걸친 공급업체 연계 거래 625건을 분석하고, 월간 단가 벤치마크로 Beef Cow Feed의 수출 경쟁력과 소싱 리스크를 추적하세요.
Beef Cow Feed 국가별 공급업체 거래 및 수출 모멘텀 전년 대비 변화
Beef Cow Feed의 긍정적/부정적 전년 대비 변화를 비교해 성장하는 공급 시장과 약화되는 수출 경로를 식별하세요.
Beef Cow Feed의 YoY 변동 상위 국가는 캐나다 (+3152.4%), 중국 (+146.1%), 아일랜드 (-80.9%)입니다.
Beef Cow Feed 국가별 공급업체 거래 및 단가 요약
2025-11 기준으로 Beef Cow Feed 국가별 거래 건수와 월간 단가/물량을 비교해 공급업체 및 수출 시장 우선순위를 정하세요.
2026-04 기준, 노출 가능한 Beef Cow Feed 거래 단가가 있는 국가는 인도 (0.21 USD / kg)입니다.
| 국가 | 전년 대비 변화 | 거래 건수 | 2025-11 | 2025-12 | 2026-01 | 2026-02 | 2026-03 | 2026-04 | 2026-05 | 2026-06 | 2026-07 | 2026-08 | 2026-09 | 2026-10 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 인도 | -3.4% | 246 | 0.20 USD / kg (5,043,449.994 kg) | 0.22 USD / kg (6,082,470.007 kg) | 0.22 USD / kg (494,189.996 kg) | 0.22 USD / kg (1,072,836.992 kg) | 0.18 USD / kg (1,072,836.992 kg) | 0.21 USD / kg (1,558,160.052 kg) | ||||||
| 코스타리카 | -22.4% | 49 | 6.57 USD / kg (53,632.704 kg) | 2.14 USD / kg (10,600 kg) | 2.48 USD / kg (22,020 kg) | 2.03 USD / kg (12,780.1 kg) | - (-) | - (-) | ||||||
| 캐나다 | +3152.4% | 23 | 7.10 USD / kg (793,878 kg) | 8.65 USD / kg (135,860 kg) | 12.66 USD / kg (244,350 kg) | 12.66 USD / kg (77,130 kg) | - (-) | - (-) | ||||||
| 카자흐스탄 | +64.4% | 3 | - (-) | - (-) | - (-) | 0.33 USD / kg (202,240 kg) | - (-) | - (-) | ||||||
| 베트남 | +53.7% | 221 | 0.19 USD / kg (2,308,050 kg) | 0.28 USD / kg (5,398,778 kg) | 0.31 USD / kg (2,995,950 kg) | - (-) | - (-) | - (-) | ||||||
| 미국 | -3.6% | 36 | 0.29 USD / kg (12,834,326 kg) | 0.25 USD / kg (7,059,426 kg) | 0.29 USD / kg (1,646,126 kg) | - (-) | - (-) | - (-) | ||||||
| 브라질 | +59.5% | 3 | 3.16 USD / kg (4,000 kg) | - (-) | 2.32 USD / kg (54,000 kg) | - (-) | - (-) | - (-) | ||||||
| 콜롬비아 | +10.8% | 10 | 1.07 USD / kg (26,933 kg) | 0.87 USD / kg (48,548.35 kg) | - (-) | - (-) | - (-) | - (-) | ||||||
| 호주 | -6.9% | 7 | - (-) | 0.37 USD / kg (1,241,350 kg) | - (-) | - (-) | - (-) | - (-) | ||||||
| 싱가포르 | - | 3 | - (-) | 0.24 USD / kg (2,098,476 kg) | - (-) | - (-) | - (-) | - (-) |
Beef Cow Feed Global Supply Chain Coverage
729개 기업
Beef Cow Feed에 대해 수출업체 331개와 수입업체 398개가 매핑되어 있습니다.
수출업체와 수입업체는 Tridge 공급망 인텔리전스의 기업 프로필 및 분석을 활용해 Beef Cow Feed 거래 상대를 식별하고, 시장 도달 범위를 벤치마킹하며, 시장별 아웃리치 우선순위를 정할 수 있습니다.
Beef Cow Feed 수출 공급업체 인텔리전스, 무역 흐름 및 가격 시그널
Beef Cow Feed에 대해 Tridge Supply Chain Intelligence에 수출업체 331개가 매핑되어 있습니다. 수출업체와 수입업체는 회사 프로필 및 분석을 활용해 공급업체 커버리지, 거래 활동, 경로 기회를 평가할 수 있습니다.
Beef Cow Feed 검증된 수출 공급업체 및 프리미엄 파트너
프리미엄 Beef Cow Feed 공급업체 3개는 국가, 산업, 연락 가능성 시그널을 포함해 신뢰할 수 있는 수출 파트너를 더 빠르게 우선순위화할 수 있게 합니다.
Hoang Anh Gia Lai Agricultural Joint Stock Company
베트남
축산, 작물 생산, 식품 제조

Barr‑Ag Ltd.
캐나다
작물 생산, 기타
Entreprises Macay Inc.
캐나다
작물 생산, 식품 제조
프리미엄 공급업체로 가입하여 Tridge 공급망 네트워크에 참여하고 마케팅 및 수출 채널 전략을 고도화하세요.
Beef Cow Feed 상위 수출업체 및 공급업체 프로필
선도 수출업체 프로필을 검토하고 Beef Cow Feed 공급망 인텔리전스 네트워크의 전체 수출업체 331개와 비교해 보세요. 수출업체와 수입업체는 회사 프로필 및 분석을 잠금 해제해 파트너를 더 빠르게 검증할 수 있습니다.
(파라과이)
최근 수출 거래: 2026-09-19
최근 수출 파트너 기업: 6
임직원 규모: 직원 1000명 초과
매출액: 매출 USD 1B 초과
산업군: 음료 제조, 작물 생산, 식품 제조, 식품 포장
밸류체인 역할: 유통 / 도매, 농업 / 생산 / 가공 / 포장, 식품 제조
수출 국가: 방글라데시, 에콰도르, 칠레, 아르헨티나, 싱가포르, 베트남, 우루과이, 브라질
공급 제품: Cattle Feed, Ethyl Alcohol, Corn Oil +3
(파라과이)
최근 수출 거래: 2026-09-19
최근 수출 파트너 기업: 3
임직원 규모: 직원 1000명 초과
산업군: 작물 생산, 식품 제조, 식품 포장
밸류체인 역할: 유통 / 도매, 농업 / 생산 / 가공 / 포장, 식품 제조
수출 국가: 방글라데시, 캐나다, 미국, 베트남, 스페인, 네덜란드, 싱가포르, 독일, 우루과이, 브라질
공급 제품: Ethyl Alcohol, Cattle Feed, Corn Oil +5
(파라과이)
최근 수출 거래: 2026-09-19
최근 수출 파트너 기업: 5
임직원 규모: 직원 1000명 초과
매출액: 매출 USD 1B 초과
산업군: 음료 제조, 작물 생산, 식품 제조, 식품 포장
밸류체인 역할: 유통 / 도매, 농업 / 생산 / 가공 / 포장, 식품 제조, 무역
수출 국가: 베트남, 태국, 아르헨티나, 브라질, 우루과이
공급 제품: Cattle Feed, Beef Cow Feed
(캐나다)
최근 수출 거래: 2026-02-13
최근 수출 파트너 기업: 1
임직원 규모: 직원 101 - 500명
매출액: 매출 USD 50M - 100M
산업군: 식품 제조, 기타
밸류체인 역할: 식품 제조, 기타
수출 국가: 인도, 미국
공급 제품: Cattle Feed, Rye, Mixed Grain Powder +4
(미국)
최근 수출 거래: 2026-02-09
최근 수출 파트너 기업: 5
산업군: 축산, 음료 제조, 식품 제조, 식품 포장, 기타
밸류체인 역할: 유통 / 도매, 농업 / 생산 / 가공 / 포장, 식품 제조, 무역
수출 국가: 말레이시아, 미국, 인도네시아, 스리랑카, 에콰도르, 방글라데시, 터키, 필리핀, 베트남, 멕시코
공급 제품: Corn Groats, Cattle Feed, Soybean Meal +5
(미국)
최근 수출 거래: 2026-09-19
최근 수출 파트너 기업: 1
임직원 규모: 직원 1000명 초과
매출액: 매출 USD 50M - 100M
산업군: 축산, 식품 제조
밸류체인 역할: 유통 / 도매, 식품 제조
수출 국가: 멕시코
공급 제품: Cattle Feed, Sugar Beet Syrup, Beef Cow Feed +1
트릿지 아이에서 전체 그림 보기: 가격·거래 전체 이력 · 725,009+ 기업 프로필
Beef Cow Feed 글로벌 수출업체 커버리지
331개 기업
수출업체 수는 Beef Cow Feed의 공급 깊이와 소싱 선택지의 핵심 신호입니다.
공급망 인텔리전스 분석을 활용해 Beef Cow Feed 기회를 국가, 제품, 밸류체인 역할로 좁힌 뒤 기업 프로필을 열어 적합성을 검증하세요.
Tridge Ark · 수입 가능성 진단
Beef Cow Feed, 어디서 들여오는 게 좋을까요?
필요한 스펙과 물량만 알려주세요. 실제로 소싱이 되는지, 어떤 원산지와 공급사가 맞는지 짚어드려요.
무료 가능성 진단은 가입 없이 받을 수 있습니다.
Beef Cow Feed 수입 바이어 인텔리전스, 수요 시그널 및 가격 벤치마크
Beef Cow Feed 수요 인텔리전스를 위해 수입업체 398개가 매핑되어 있습니다. Supply Chain Intelligence 회사 프로필 및 분석으로 시장별 바이어, 유통업체, 다운스트림 수요 파트너의 우선순위를 정하세요.
Beef Cow Feed 상위 바이어, 수입업체 및 수요 파트너
선도 바이어 프로필을 검토하고 Beef Cow Feed에 대해 추적되는 전체 수입업체 398개와 비교해 보세요. 수출업체와 수입업체는 Supply Chain Intelligence 회사 프로필 및 분석을 활용해 바이어 품질과 수요 집중도를 평가할 수 있습니다.
(베트남)
최근 수입 거래: 2026-01-05
최근 수입 파트너 기업: 3
임직원 규모: 직원 1000명 초과
산업군: 축산, 음료 제조, 식품 제조, 식품 포장, 식음료 서비스업
밸류체인 역할: 스웨덴, 대한민국
(우루과이)
최근 수입 거래: 2026-09-19
최근 수입 파트너 기업: 1
임직원 규모: 직원 11 - 50명
매출액: 매출 USD 5M - 10M
산업군: 음료 제조, 작물 생산, 식품 제조, 식품 포장, 식품 도매, 기타
밸류체인 역할: 감비아, 베트남, 멕시코, 대만, 브라질, 중국, 파라과이, 인도
(칠레)
최근 수입 거래: 2026-09-19
최근 수입 파트너 기업: 1
임직원 규모: 직원 51 - 100명
산업군: 브로커 및 무역 대행, 작물 생산, 식품 제조
밸류체인 역할: 콜롬비아
(멕시코)
최근 수입 거래: 2026-09-19
최근 수입 파트너 기업: 1
임직원 규모: 직원 51 - 100명
산업군: 음료 제조, 식품 제조, 식품 포장
밸류체인 역할: 영국, 미국
(베트남)
최근 수입 거래: 2026-09-19
최근 수입 파트너 기업: 2
산업군: 브로커 및 무역 대행, 작물 생산, 식품 제조
밸류체인 역할: 싱가포르, 베트남, 캄보디아, 필리핀
(일본)
최근 수입 거래: 2026-02-13
최근 수입 파트너 기업: 1
임직원 규모: 직원 101 - 500명
산업군: 축산, 식품 제조, 식품 도매
밸류체인 역할: -
트릿지 아이에서 전체 그림 보기: 가격·거래 전체 이력 · 725,009+ 기업 프로필
글로벌 수입업체 커버리지
398개 기업
수입업체 수는 Beef Cow Feed에 대한 수요 측 가시성의 현재 깊이를 보여줍니다.
공급망 인텔리전스 분석과 기업 프로필을 활용해 활동 중인 Beef Cow Feed 바이어를 식별하고, 국가별 파트너 밀도를 비교하며, GTM 우선순위를 정교화하세요.
Tridge Ark · 수출 가능성 진단
우리 Beef Cow Feed, 어느 바이어에게 팔 수 있을까요?
만드시는 제품만 알려주시면 됩니다. 지금 수출할 준비가 됐는지, 어느 시장이 맞는지 봐드려요.
무료 가능성 진단은 가입 없이 받을 수 있습니다.
Classification
Product TypeIndustrial Product
Product FormCompound feed (pelleted or mash)
Industry PositionManufactured Agricultural Input
Market
Beef cow feed is a manufactured livestock input whose economics are dominated by the availability and price of feed grains, oilseed meals, and forage substitutes. Most volume is produced domestically near cattle operations because finished feed is bulky, while cross-border trade tends to concentrate in higher-value premixes, supplements, and specialty formulations. Key production centers align with large beef and feed-grain systems including the United States, Brazil, China, and major EU member states, with additional scale in India, Mexico, and Russia. Global market dynamics are heavily influenced by weather-driven grain yield variability, Black Sea and Americas logistics disruptions, and tightening sustainability due diligence expectations for soy-linked supply chains.
Market GrowthMixed (medium-term outlook)Demand tracks cattle numbers and feedlot intensity, while formulation shifts respond to grain price cycles and byproduct availability.
Major Producing Countries
- 중국Large compound feed manufacturing base; significant internal demand for livestock production.
- 미국Major feed grain producer and large cattle industry; substantial commercial feed and premix sector.
- 브라질Large soybean/corn supply base supporting feed manufacturing; major beef production system.
- 인도Large feed manufacturing footprint within a large livestock economy; formulations vary by region and system.
- 멕시코Significant cattle and feed demand with dependence on imported feed ingredients in some years.
- 러시아Large grain producer and compound feed manufacturing capacity serving domestic livestock sectors.
- 스페인One of the largest compound feed producers within the EU; relevant to regional trade of feed and premixes.
- 독일Large compound feed and premix industry within the EU; strong feed safety and certification presence.
Supply Calendar
- United States (corn/soy supply):Sep, Oct, Nov, DecPost-harvest availability of key energy/protein inputs commonly used in cattle rations increases in Q4.
- Brazil (soybean and second-crop corn supply):Feb, Mar, Apr, May, Jun, Jul, AugSoybean harvest typically concentrates in late Q1–Q2; second-crop corn marketing often strengthens mid-year.
- Argentina (corn/soy supply):Mar, Apr, May, Jun, JulSouthern Hemisphere harvest period supports mid-year availability of feed ingredients exported to global markets.
- France (wheat/barley supply):Jul, Aug, Sep, OctEU grain harvest period shapes regional feed ingredient availability and pricing into early autumn.
- Australia (wheat/barley supply):Nov, Dec, Jan, FebSouthern Hemisphere grain harvest supports availability into the Northern Hemisphere winter.
Specification
Physical Attributes
- Pellet diameter and durability (or mash particle size distribution) tailored to feeding system and intake targets
- Low dust/fines to improve handling and reduce segregation during transport and feeding
- Moisture control to reduce mold growth and caking during storage
Compositional Metrics
- Guaranteed analysis or buyer specification parameters such as crude protein, crude fat, crude fiber, and ash
- Fiber and energy metrics used in ruminant formulation (e.g., NDF/ADF, starch, net energy proxies) depending on the market and system
- Macro- and micro-mineral targets (e.g., calcium/phosphorus balance, salt) and vitamin inclusion via premixes
- Mycotoxin screening/management requirements for grain-based inputs depending on origin and season
Grades
- Commercial specifications are commonly expressed as label guarantees and buyer contracts rather than a single universal global grade system
- Third-party feed safety schemes may be required by buyers in some markets (scheme choice varies by region)
Packaging
- Bulk delivery via truck or rail for feedlots and large operations
- Bagged formats (e.g., 25–50 kg) for smaller commercial channels and farm distribution
- FIBC/"big bag" formats for supplements and some concentrates where applicable
ProcessingGrinding and mixing uniformity are critical to prevent nutrient segregation and uneven intakeHeat conditioning and pelleting can improve handling and reduce microbial load, but requires moisture and temperature control to protect heat-sensitive vitaminsInclusion of liquids (e.g., molasses, fats) affects pellet quality, palatability, and storage stability
Supply Chain
Value Chain
- Procurement of grains/oilseed meals/byproducts and premixes → intake testing (e.g., moisture, mycotoxin screens) → grinding → batching and mixing → conditioning → pelleting (or mash finishing) → cooling → post-pellet liquid application (optional) → bulk/bag packaging → distribution to feedlots/ranches
Demand Drivers
- Cattle production levels and feedlot placement rates in major beef-producing regions
- Relative prices of maize/corn, soybean meal, and competing ingredients driving ration reformulation
- Drought and pasture shortfalls increasing supplemental feeding and concentrate demand
- Availability of industrial byproducts used in rations (e.g., DDGS, wheat midds) and local logistics costs
Temperature
- Finished feed is generally ambient-stable but requires cool, dry storage to limit mold growth and nutrient degradation
- Moisture ingress during transport or storage can trigger clumping, heating, and spoilage risk
Shelf Life
- Shelf life depends on moisture, fat content, and vitamin stability; many formulations are managed on a first-in/first-out basis with turnover targeted to weeks-to-months depending on climate and storage conditions
- Higher-fat or molasses-containing products may have shorter practical storage windows due to rancidity or caking risk
Risks
Feed Ingredient Supply Shock HighBeef cow feed costs and availability can be rapidly disrupted by weather-driven yield losses and geopolitical/logistics shocks in major feed grain and oilseed exporting regions, driving sudden price spikes and forcing ration reformulation or reduced feeding intensity.Diversify ingredient baskets and origins where feasible, use forward purchasing/hedging policies, and qualify substitute inputs and premixes in advance.
Feed Safety HighMycotoxin contamination (e.g., aflatoxins and trichothecenes in maize and other grains) can reduce animal performance, create residue/food safety concerns, and trigger rejection of raw materials or finished feed in regulated markets.Implement risk-based incoming testing, origin/season risk profiling, storage moisture control, and validated mycotoxin mitigation strategies consistent with local regulations.
Regulatory Compliance MediumCattle feed regulation can restrict certain animal-derived proteins due to BSE-related controls, and impose labeling, additive approvals, and cross-contamination prevention requirements that vary materially by jurisdiction.Maintain robust HACCP-like feed safety programs, segregate ruminant-restricted materials where applicable, and keep up-to-date regulatory dossiers for additives and claims in target markets.
Sustainability And Traceability MediumDeforestation-related due diligence and traceability expectations for soy-linked supply chains can affect access to premium markets and increase compliance costs for feed manufacturers and traders.Adopt supplier traceability requirements for soy and high-risk inputs, align sourcing with credible certification/verification approaches, and maintain auditable documentation for buyers and regulators.
Logistics MediumBulk transport disruptions (port congestion, inland freight constraints, and container availability for premixes) can delay ingredient arrivals and finished feed deliveries, impacting feedlot continuity and animal performance.Build contingency inventories for critical premixes/additives, qualify multiple carriers and routes, and use demand forecasting tied to cattle placements and seasonality.
Sustainability
- Land-use change and deforestation risk linked to soybean expansion in parts of South America affecting feed ingredient sourcing expectations
- Greenhouse gas footprint considerations across the beef value chain, with feed efficiency and ingredient sourcing under increasing scrutiny
- Nutrient runoff and fertilizer-related impacts associated with large-scale feed grain production
Labor & Social
- Supply-chain due diligence expectations (traceability, responsible sourcing) increasingly applied to soy- and cocoa-like high-risk land-use commodities; for cattle feed this most directly affects soy-linked inputs and premix supply chains
- Animal welfare and responsible production expectations can influence buyer standards for feeding practices and ingredient sourcing
FAQ
What are common inputs used to manufacture beef cow feed globally?Globally, beef cow feed formulations commonly draw on feed grains (especially maize/corn and sometimes wheat or barley), oilseed meals (notably soybean meal), industrial byproducts such as DDGS where available, and mineral/vitamin premixes. The exact recipe varies by region, cattle system (cow-calf vs. feedlot), and relative ingredient prices.
What is the most critical risk that can disrupt beef cow feed availability or cost worldwide?The most critical risk is a sudden shock to the supply or price of core feed ingredients like maize/corn and soybean products due to extreme weather or major logistics/geopolitical disruptions in key exporting regions. Because feed is a primary cost input in beef production, these shocks can quickly force ration changes, reduce feeding intensity, or raise beef production costs.
Why do many markets restrict certain animal-derived materials in cattle feed?Many jurisdictions restrict specific animal-derived proteins in cattle feed due to BSE-related controls and to prevent cross-contamination. This makes regulatory compliance, ingredient segregation, and documented feed safety programs important for manufacturers and traders serving multiple markets.
Sources
Beef Cow Feed 공급업체, 수출 흐름, 가격 데이터 국가 커버리지
공급업체 커버리지, 무역 흐름, 가격 벤치마크를 위해 Beef Cow Feed의 국가별 마켓 페이지를 탐색하세요.


Tridge Ark · 수출·수입 가능성 진단
Beef Cow Feed, 사는 쪽이세요 파는 쪽이세요?
어느 쪽이든 몇 가지만 답해주시면 됩니다. 어디서 살 수 있는지, 누구에게 팔 수 있는지 정리해서 보내드릴게요.
무료 가능성 진단은 가입 없이 받을 수 있습니다.
'쿠키 허용'을 클릭하면 통계 및 개인 선호도 산출을 위한 쿠키 제공에 동의하게 됩니다.
개인정보 보호정책에서 쿠키에 대한 자세한 내용을 확인할 수 있습니다.