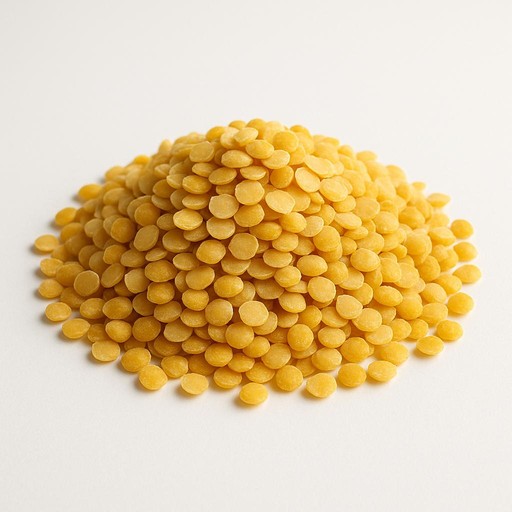
Dried Split Yellow Lentils Suppliers, Trade & Prices — Market Overview 2026
Parent Product
Dried Lentil
HS Code
071340
Last Updated
2026-10-02
Key takeaways for search and sourcing teams
- Dried Split Yellow Lentils market coverage spans 138 countries.
- 219 exporter companies and 353 importer companies are indexed in the global supply chain intelligence network for this product.
- 374 supplier-linked transactions are summarized across the top 6 countries.
- Latest reference year in this page dataset is 2024.
- Page data last updated on 2026-10-02.
Global Supplier Transactions, Export Activity, and Price Benchmarks for Dried Split Yellow Lentils
Analyze 374 supplier-linked transactions across the top 6 countries, with monthly unit-price benchmarks to track export competitiveness and sourcing risk for Dried Split Yellow Lentils.
Dried Split Yellow Lentils Country YoY Change in Supplier Transactions and Export Momentum
Compare positive and negative YoY shifts in Dried Split Yellow Lentils to identify accelerating supplier markets and weakening export corridors.
Top YoY shifts for Dried Split Yellow Lentils: Sri Lanka (+129.8%), Chile (-42.5%), Canada (-39.6%).
Dried Split Yellow Lentils Country-Level Supplier Transaction and Unit Price Summary
As of 2025-11, benchmark Dried Split Yellow Lentils country transaction counts with monthly unit price and volume to prioritize supplier and export markets.
In 2026-04, countries with visible Dried Split Yellow Lentils transaction unit prices: India (1.81 USD / kg), Chile (1.30 USD / kg), Argentina (0.91 USD / kg), Canada (0.61 USD / kg), United States (0.59 USD / kg).
| Country | YoY Change | Transaction Count | 2025-11 | 2025-12 | 2026-01 | 2026-02 | 2026-03 | 2026-04 | 2026-05 | 2026-06 | 2026-07 | 2026-08 | 2026-09 | 2026-10 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| India | -3.1% | 128 | 2.14 USD / kg (21,971.18 kg) | 2.39 USD / kg (11,231.5 kg) | 1.64 USD / kg (105,636.77 kg) | 1.89 USD / kg (60,053.798 kg) | 2.19 USD / kg (60,891.44 kg) | 1.81 USD / kg (186,941.14 kg) | ||||||
| Canada | -39.6% | 203 | 0.87 USD / kg (1,166,678 kg) | 0.77 USD / kg (914,570 kg) | 0.61 USD / kg (1,316,350 kg) | 0.59 USD / kg (1,826,250 kg) | 0.64 USD / kg (2,800,475 kg) | 0.61 USD / kg (1,667,075 kg) | ||||||
| United States | -38.0% | 24 | 0.70 USD / kg (25,000 kg) | 0.87 USD / kg (105,200 kg) | 0.64 USD / kg (74,700 kg) | 0.64 USD / kg (130,550 kg) | 0.64 USD / kg (149,300 kg) | 0.59 USD / kg (84,151.81 kg) | ||||||
| Chile | -42.5% | 17 | 2.29 USD / kg (2,999.24 kg) | 1.15 USD / kg (1,200 kg) | 0.70 USD / kg (202 kg) | 1.25 USD / kg (1,300 kg) | 1.18 USD / kg (300 kg) | 1.30 USD / kg (3,400 kg) | ||||||
| Argentina | +4.1% | 1 | - (-) | - (-) | - (-) | - (-) | - (-) | 0.91 USD / kg (27,500 kg) | ||||||
| Sri Lanka | +129.8% | 1 | - (-) | - (-) | 2.00 USD / kg (2,650 kg) | - (-) | - (-) | - (-) |
Dried Split Yellow Lentils Global Supply Chain Coverage
572 companies
219 exporters and 353 importers are mapped for Dried Split Yellow Lentils.
Exporters and importers can use Tridge Supply Chain Intelligence company profiles and analytics to identify counterparties for Dried Split Yellow Lentils, benchmark reach, and prioritize outreach by market.
Dried Split Yellow Lentils Export Supplier Intelligence, Trade Flows, and Price Signals
219 exporter companies are mapped in Tridge Supply Chain Intelligence for Dried Split Yellow Lentils. Exporters and importers can use company profiles and analytics to evaluate supplier coverage, trading activity, and route opportunities.
Dried Split Yellow Lentils Top Exporters and Supplier Profiles
Review leading exporter profiles while benchmarking against 219 total exporter companies in the Dried Split Yellow Lentils supply chain intelligence network. Exporters and importers can unlock company profiles and analytics to qualify partners faster.
(Turkiye)
Latest Export Transaction: 2026-09-02
Recently Export Partner Companies: 13
Employee Size: 101 - 500 Employees
Industries: Food Manufacturing, Food Packaging, Food Wholesalers
Value Chain Roles: Distribution / Wholesale, Farming / Production / Processing / Packing, Food Manufacturing, Trade
Exporting Countries: Netherlands, Algeria, Russia, Egypt, Tunisia, Turkiye, India, Sudan, Italy, Germany
Supplying Products: Dried Lentil, Wheat Grain, Bulgur +5
(Turkiye)
Latest Export Transaction: 2026-09-02
Recently Export Partner Companies: 12
Employee Size: Over 1000 Employees
Sales Revenue: USD Over 1B
Industries: Crop Production, Food Manufacturing, Food Wholesalers
Value Chain Roles: Distribution / Wholesale, Farming / Production / Processing / Packing, Food Manufacturing
Exporting Countries: Egypt, Ukraine, Lebanon, United Kingdom, India, Switzerland, Italy, Sudan, Algeria, Iraq
Supplying Products: Dried Lentil, Dried Peas, Dried Chickpea +5
(Turkiye)
Latest Export Transaction: 2026-09-02
Recently Export Partner Companies: 2
Industries: Beverage Manufacturing, Food Manufacturing, Food Packaging, Food Wholesalers, Others
Value Chain Roles: Distribution / Wholesale, Farming / Production / Processing / Packing, Food Manufacturing
Exporting Countries: New Zealand, United States, Hungary, Spain, Poland, Portugal, France, Netherlands, Germany, Italy
Supplying Products: Dried Lentil, Apple Juice Concentrate, Bulgur +5
(Turkiye)
Latest Export Transaction: 2026-09-02
Recently Export Partner Companies: 14
Employee Size: Over 1000 Employees
Industries: Food Manufacturing
Value Chain Roles: Distribution / Wholesale, Farming / Production / Processing / Packing, Food Manufacturing
Exporting Countries: Iran, Iraq, Morocco, Ukraine, France, Israel, Algeria, Sudan, Italy, Turkiye
Supplying Products: Dried Lentil, Paddy Rice, Wheat Grain +5
(Turkiye)
Latest Export Transaction: 2026-09-02
Recently Export Partner Companies: 6
Employee Size: Over 1000 Employees
Industries: Food Manufacturing
Value Chain Roles: Distribution / Wholesale, Food Manufacturing
Exporting Countries: Denmark, Switzerland, Romania, Belgium, France, United Kingdom, Germany, Italy, United States, United Arab Emirates
Supplying Products: Corn Meal, Dried Soybean, Sunflower Oil +5
(India)
Latest Export Transaction: 2026-07-10
Recently Export Partner Companies: 1
Employee Size: Over 1000 Employees
Sales Revenue: USD Over 1B
Industries: Beverage Manufacturing, Crop Production, Food Manufacturing, Food Services And Drinking Places, Others
Value Chain Roles: Distribution / Wholesale, Farming / Production / Processing / Packing, Food Manufacturing, Retail, Trade
Exporting Countries: Angola, Egypt, South Korea, Senegal, Guinea, Turkiye, Togo, Benin, Yemen, Saudi Arabia
Supplying Products: Parboiled Rice, Sesame Seed, Milled Rice +5
See the full picture in Tridge Eye: full price and trade history · 725,009+ company profiles
Dried Split Yellow Lentils Global Exporter Coverage
219 companies
Exporter company count is a key signal for Dried Split Yellow Lentils supply depth and sourcing optionality.
Use Supply Chain Intelligence analytics to narrow Dried Split Yellow Lentils opportunities by country, product, and value-chain role, then open company profiles to validate fit.
Top Exporting Countries for Dried Split Yellow Lentils (HS Code 071340) in 2024
For Dried Split Yellow Lentils in 2024, compare export volume and value across the top 10 supplier countries to map core supply structure.
| Rank | Country | Volume | Value |
|---|---|---|---|
| 1 | Canada | 1,915,910,884 kg | 1,622,109,634.733 USD |
| 2 | Australia | 1,342,428,391.88 kg | 831,120,760.035 USD |
| 3 | Turkiye | 648,434,289 kg | 626,755,800 USD |
| 4 | United States | 296,543,675 kg | 307,351,167 USD |
| 5 | India | 168,505,325 kg | 148,657,139.041 USD |
| 6 | Egypt | 23,431,224.736 kg | 27,475,958.968 USD |
| 7 | Netherlands | 12,064,697 kg | 22,643,237.949 USD |
| 8 | Italy | 6,692,212 kg | 12,336,262.582 USD |
| 9 | Ukraine | 16,235,757.06 kg | 9,531,871.39 USD |
| 10 | Czechia | 4,205,637 kg | 7,251,014 USD |
Dried Split Yellow Lentils Export Trade Flow and Partner Country Summary
Track Dried Split Yellow Lentils exporter-to-importer flows by value, volume, and share to uncover high-potential export routes.
Sourcing diagnosis
Where should you be sourcing Dried Split Yellow Lentils from?
Just tell us your spec and the volume you need. We'll check whether it's actually sourceable, and which origins and suppliers fit.
Free diagnosis, no account required.
Dried Split Yellow Lentils Import Buyer Intelligence, Demand Signals, and Price Benchmarks
353 importer companies are mapped for Dried Split Yellow Lentils demand intelligence. Use Supply Chain Intelligence company profiles and analytics to prioritize buyers, distributors, and downstream demand partners by market.
Dried Split Yellow Lentils Top Buyers, Importers, and Demand Partners
Review leading buyer profiles and compare them against 353 total importer companies tracked for Dried Split Yellow Lentils. Exporters and importers can use Supply Chain Intelligence company profiles and analytics to evaluate buyer quality and demand concentration.
(Chile)
Latest Import Transaction: 2026-06-26
Recently Import Partner Companies: 3
Sales Revenue: USD 5M - 10M
Industries: Food Manufacturing, Food Services And Drinking Places, Food Wholesalers
Value Chain Roles: Vietnam, Italy, United Arab Emirates, Mexico, Peru, Colombia, Netherlands, Brazil, Germany, India
(Chile)
Latest Import Transaction: 2026-06-25
Recently Import Partner Companies: 3
Employee Size: 101 - 500 Employees
Sales Revenue: USD 10M - 50M
Industries: Beverage Manufacturing, Brokers And Trade Agencies, Crop Production, Food Manufacturing, Food Packaging, Food Wholesalers
Value Chain Roles: Spain
(Chile)
Latest Import Transaction: 2026-06-25
Recently Import Partner Companies: 3
Employee Size: Over 1000 Employees
Sales Revenue: USD Over 1B
Industries: Food Manufacturing, Food Packaging
Value Chain Roles: Argentina, Brazil, Turkiye
(Italy)
Latest Import Transaction: 2026-09-02
Recently Import Partner Companies: 1
Employee Size: 101 - 500 Employees
Sales Revenue: USD 10M - 50M
Industries: Crop Production, Food Manufacturing, Food Packaging
Value Chain Roles: United States, Ukraine, Pakistan, Turkiye
(Italy)
Latest Import Transaction: 2026-09-02
Recently Import Partner Companies: 1
Employee Size: 101 - 500 Employees
Industries: Food Manufacturing, Others
Value Chain Roles: Mexico, South Korea, Turkiye, Colombia, United States
(India)
Latest Import Transaction: 2026-09-02
Recently Import Partner Companies: 1
Employee Size: Over 1000 Employees
Sales Revenue: USD Over 1B
Industries: Beverage Manufacturing, Brokers And Trade Agencies, Crop Production, Food Manufacturing, Food Packaging, Others
Value Chain Roles: Mauritius, South Africa, Singapore, China, Bangladesh, United Arab Emirates, Sri Lanka, Malaysia, Turkiye, Algeria
See the full picture in Tridge Eye: full price and trade history · 725,009+ company profiles
Global Importer Coverage
353 companies
Importer company count highlights the current depth of demand-side visibility for Dried Split Yellow Lentils.
Use Supply Chain Intelligence analytics and company profiles to identify active Dried Split Yellow Lentils buyers, compare partner density by country, and refine GTM priorities.
Top Import Demand Countries for Dried Split Yellow Lentils (HS Code 071340) in 2024
For Dried Split Yellow Lentils in 2024, compare import volume and value across the top 10 demand countries to identify priority markets.
| Rank | Country | Volume | Value |
|---|---|---|---|
| 1 | India | 1,060,260,182 kg | 811,004,406.398 USD |
| 2 | Turkiye | 646,548,539 kg | 459,818,126 USD |
| 3 | Egypt | 126,937,060.614 kg | 165,770,960.807 USD |
| 4 | Pakistan | 180,958,342 kg | 129,885,594.956 USD |
| 5 | Sri Lanka | 164,885,489.075 kg | 122,769,834.817 USD |
| 6 | Canada | 119,437,655.317 kg | 108,479,754.412 USD |
| 7 | United States | 87,653,829 kg | 85,628,818 USD |
| 8 | Mexico | 60,596,269 kg | 64,963,915 USD |
| 9 | Spain | 48,652,141.296 kg | 57,368,826.342 USD |
| 10 | Germany | 23,203,245.116 kg | 34,039,927.043 USD |
Dried Split Yellow Lentils Import Trade Flow and Origin Country Summary
Analyze Dried Split Yellow Lentils origin-to-destination trade flows by value, volume, and share to monitor demand-side sourcing channels.
Export diagnosis
Your Dried Split Yellow Lentils — which buyers could it sell to?
Just tell us what you make. We'll see whether you're ready to export today and which markets suit your offer.
Free diagnosis, no account required.
Price data
Which Dried Split Yellow Lentils prices do you need?
We'll open up the full price history and competitor benchmarks. Just tell us which numbers you need and we'll walk you through them.
Classification
Product TypeRaw Material
Product FormDried (Dehulled & Split)
Industry PositionSemi-processed Agricultural Commodity
Raw Material
Commodity GroupPulses (grain legumes)
Scientific NameLens culinaris
PerishabilityLow (dried commodity; quality is moisture- and pest-sensitive).
Growing Conditions
- Cool-season annual crop; commonly grown in temperate and semi-arid regions
- Prefers well-drained soils; sensitive to waterlogging
- Yield and quality are sensitive to drought/heat stress during key growth stages
Main VarietiesRed lentil market class (commonly processed into splits), Green lentil market class, Brown lentil market class
Consumption Forms
- Cooked lentil dishes (e.g., dals, soups, stews)
- Food ingredient in prepared foods and convenience meals
- Milled into lentil flour for formulations
Grading Factors
- Moisture content
- Foreign matter
- Split integrity (broken/splinter percentage)
- Color uniformity
- Damaged/blemished kernels
- Insect infestation and insect damage
- Metal/stone contamination control
Planting to HarvestAnnual crop; harvested within one growing season (timing varies by region and cultivar).
Market
Dried split yellow lentils are a globally traded pulse product positioned between farm-gate pulses and packaged retail foods, with value added through cleaning, dehulling, splitting, and sorting. Export availability is strongly influenced by large temperate-origin pulse industries—especially Canada and Australia—while major demand centers include South Asia and the Middle East/North Africa where lentils are staple proteins. Trade flows are sensitive to crop-year weather outcomes in key exporters and to import-policy changes in major consuming markets, which can rapidly re-route global shipments. The product’s relatively long shelf life enables containerized bulk trade, but quality and compliance depend on moisture control, storage pest management, and meeting importing-country residue/contaminant limits.
Major Producing Countries
- CanadaAmong the largest global lentil producers and a key origin for exportable supply used in both whole and split forms.
- IndiaMajor producer and the world’s largest lentil-consuming market; also a major importer depending on domestic crop outcomes and policy.
- AustraliaMajor pulse producer with significant export orientation; Southern Hemisphere season complements Northern origins.
- TurkiyeImportant producing and processing country in regional lentil trade, including splitting and re-export activity.
- United StatesNotable producer (Pacific Northwest) and exporter, with production variability by season.
- RussiaSignificant pulse production base; participates in export markets depending on crop and trade conditions.
- KazakhstanGrowing pulse production and export participation in Eurasian corridors.
Major Exporting Countries
- CanadaLeading exporter for lentils in global trade; supplies both direct-consumption and processing markets.
- AustraliaMajor exporter supplying South Asia, MENA, and other destinations; counter-seasonal to Northern Hemisphere origins.
- TurkiyeRegional exporter and processing hub (cleaning/splitting), including re-export flows.
- United StatesExports from Pacific Northwest production; participates in niche and regional demand channels.
- RussiaExporter participation varies with crop size and trade access.
Major Importing Countries
- IndiaLargest demand center; import volumes can swing materially with domestic crop outcomes and policy settings.
- BangladeshLarge pulse-consuming market reliant on imports for lentil supply.
- PakistanSignificant importer for food consumption and processing channels.
- TurkiyeImports to balance supply and feed domestic splitting/processing and re-export pipelines.
- United Arab EmiratesTrade and re-export hub serving regional consumer markets.
- EgyptLarge food staple importer where pulses are important dietary proteins.
Supply Calendar
- Canada (Prairie provinces):Aug, SepMain harvest and export program typically follows late-summer harvest; shipment cadence depends on post-harvest conditioning and logistics.
- United States (Pacific Northwest):Aug, SepNorthern Hemisphere late-summer harvest window broadly aligned with Canada.
- Turkey (Anatolia):Jun, JulEarlier Northern Hemisphere harvest timing can provide mid-year availability for regional buyers.
- Australia (southern grain belt):Nov, DecSouthern Hemisphere harvest supports counter-seasonal export supply into the first half of the following calendar year.
- India (rabi season, by region):Mar, AprDomestic harvest timing influences import needs and price direction in a key consuming market.
Specification
Major VarietiesRed lentil market class (commonly dehulled/split), Green lentil market class (sometimes dehulled/split for specific uses), Brown lentil market class (primarily whole; some processing into splits/flour)
Physical Attributes
- Split, dehulled cotyledons with yellow appearance; uniform color is a key quality signal
- Low broken/splinter percentage preferred by many buyers for cooking performance and appearance
- Freedom from live/dead insects and insect-damaged kernels is critical for trade acceptance
Compositional Metrics
- Moisture specification (expressed as a maximum) is a common contract parameter because moisture drives mold and storage pest risk
- Foreign matter and damaged kernel tolerances are core commercial metrics used in grading and claims management
Grades
- Contract grades typically reference: moisture maximum, foreign matter maximum, defects/damage limits, and color/size uniformity (definitions vary by origin and buyer)
Packaging
- Bulk export formats: woven polypropylene (PP) bags (e.g., 25–50 kg), and flexible intermediate bulk containers (FIBCs/super sacks)
- Retail/consumer formats (destination-packed): small bags or pouches, often under private label
ProcessingCommon processing sequence: receiving/cleaning → grading → dehulling → splitting → polishing/aspiration → color sorting → final gradingProcessing yield and final appearance depend on incoming seed coat condition, kernel hardness, and equipment settings
Supply Chain
Value Chain
- Farm production → aggregation/elevator handling → cleaning and grading → dehulling & splitting → color sorting and final grade-out → bagging → containerized export → destination wholesaler/packer → retail/foodservice
Demand Drivers
- Staple protein demand in South Asia and parts of the Middle East/North Africa
- Price-competitive plant protein for soups, stews, and convenience foods
- Food aid and institutional procurement of shelf-stable pulses in some markets
Temperature
- Ambient storage and transport are typical; quality protection depends on cool, dry conditions and avoiding condensation/moisture ingress
- Storage pest control (monitoring and treatment where permitted) is often more critical than temperature setpoints
Shelf Life
- Generally long shelf life under dry, pest-controlled storage; shelf life degrades with moisture uptake, infestation, and oxidation/quality loss in poor storage conditions
Risks
Climate HighWeather-driven yield shocks (notably drought and heat) in major export-oriented origins can sharply reduce exportable supply and trigger global price volatility, affecting downstream availability for staple-demand markets and processors.Diversify origins across hemispheres (e.g., Canada/US vs. Australia/Turkey), use forward coverage aligned to crop calendars, and maintain flexible specifications and safety stocks where feasible.
Trade Policy Volatility HighImport duty changes, quota adjustments, or other policy shifts in major consuming markets can rapidly re-route global flows and change spot pricing, creating contract and inventory risk for traders and processors.Monitor policy signals and tariff schedules in major demand centers; structure contracts with clear shipment windows and contingency clauses; avoid over-concentration on a single destination.
Food Safety MediumNon-compliance with importing-country limits (e.g., pesticide residues, contaminants, or adulteration/foreign matter) can cause rejections, detentions, or reputational damage, particularly for bulk commodities moving through multiple handlers.Implement supplier approval, lot traceability, and pre-shipment testing aligned to destination requirements; strengthen cleaning, metal detection, and color sorting in processing.
Storage Pests MediumInfestation risk during storage and transit can lead to claims, rejections, and added treatment costs; resistance to common treatments can increase control difficulty.Use integrated pest management: sanitation, sealed packaging where appropriate, monitoring, and compliant treatment/fumigation protocols with verified efficacy.
Logistics MediumContainer availability, port congestion, and inland freight constraints can delay shipments and increase costs, with knock-on impacts on inventory planning for high-throughput staple markets.Maintain multiple routing options and freight partners; schedule shipments around peak export seasons; build buffer time into delivery commitments.
Sustainability
- Climate variability (drought/heat) affecting pulse yields in key exporting origins and increasing year-to-year supply volatility
- Storage-loss risk and associated fumigation practices; increasing scrutiny of pest management methods and resistance management
- Water stewardship and soil health in rainfed pulse systems; lentils are often part of crop rotations that can support soil nitrogen management
Labor & Social
- Smallholder livelihood sensitivity in major consuming/producing regions where pulses are important dietary staples and farm cash crops
- Worker safety considerations in storage, handling, and fumigation operations (where fumigants are used)
FAQ
What does “split yellow lentils” mean in trade terms?It generally refers to lentils that have been cleaned, dehulled (seed coat removed), and split into cotyledons; buyers commonly evaluate color uniformity, broken percentage, moisture, and foreign matter as key quality indicators.
Which countries are major exporters of lentils used for split products?Canada and Australia are major export-oriented origins in global lentil trade, with additional export and processing activity in countries such as Turkey and the United States depending on crop outcomes and trade conditions.
What is the biggest supply risk for this product globally?Weather-driven yield shocks in major exporting origins can sharply reduce exportable supply and trigger price volatility, which then affects availability for staple-demand markets and processors.
Sources
Dried Split Yellow Lentils Country Coverage for Suppliers, Export Flows, and Prices
Explore country-level Dried Split Yellow Lentils market pages for supplier coverage, trade flows, and price benchmarks.

Canada

India

Australia

Turkiye

United States

United Arab Emirates

Ethiopia

Malaysia

Spain

Nigeria

Belgium

Kazakhstan
All country market pages: Pakistan, France, United Kingdom, Kenya, Netherlands, Egypt, Mexico, Tanzania, Czechia, Germany, Nepal, Iran, Italy, Qatar, Zambia, Bulgaria, Malawi, China, Maldives, Bahrain, Sweden, Uganda, Kyrgyzstan, Saudi Arabia, Hungary, Denmark, Poland, Portugal, Sri Lanka, Ukraine, Colombia, Morocco, Austria, Peru, Slovakia, Greece, Myanmar [Burma], Estonia, Ecuador, Chile, Brazil, Jordan, South Africa, Norway, Serbia, Kuwait, Singapore, Malta, Latvia, Oman, Lithuania, Panama, Costa Rica, Israel, Switzerland, Slovenia, Thailand, Azerbaijan, Andorra, Albania, Armenia, Argentina, Bosnia and Herzegovina, Barbados, Burkina Faso, Burundi, Benin, Bermuda, Brunei, Bolivia, Bahamas, Botswana, Belize, Democratic Republic of the Congo, Ivory Coast, Cuba, Cyprus, Dominican Republic, Finland, Fiji, Gabon, Georgia, Gambia, Guinea, Guatemala, Hong Kong, Honduras, Croatia, Indonesia, Ireland, Iraq, Iceland, Jamaica, Japan, Cambodia, South Korea, Laos, Liberia, Lesotho, Luxembourg, Moldova, Montenegro, Madagascar, Macedonia, Mongolia, Macao, Mauritius, Mozambique, Namibia, Niger, Nicaragua, New Zealand, Philippines, Paraguay, Romania, Senegal, Suriname, El Salvador, Swaziland, Togo, Tunisia, Uruguay, Uzbekistan, Saint Vincent and the Grenadines, Vietnam, Zimbabwe
Export & sourcing diagnosis
Dried Split Yellow Lentils — are you buying, or selling?
Either way it's a few questions. We'll come back with where you could buy it, or who you could sell it to.
Free diagnosis, no account required.
Related Dried Split Yellow Lentils Product Categories
Browse parent, sub, derived, and raw-material product market pages related to Dried Split Yellow Lentils.
Parent product: Dried Lentil
By clicking “Accept Cookies,” I agree to provide cookies for statistical and personalized preference purposes. To learn more about our cookies, please read our Privacy Policy.